
Notizia
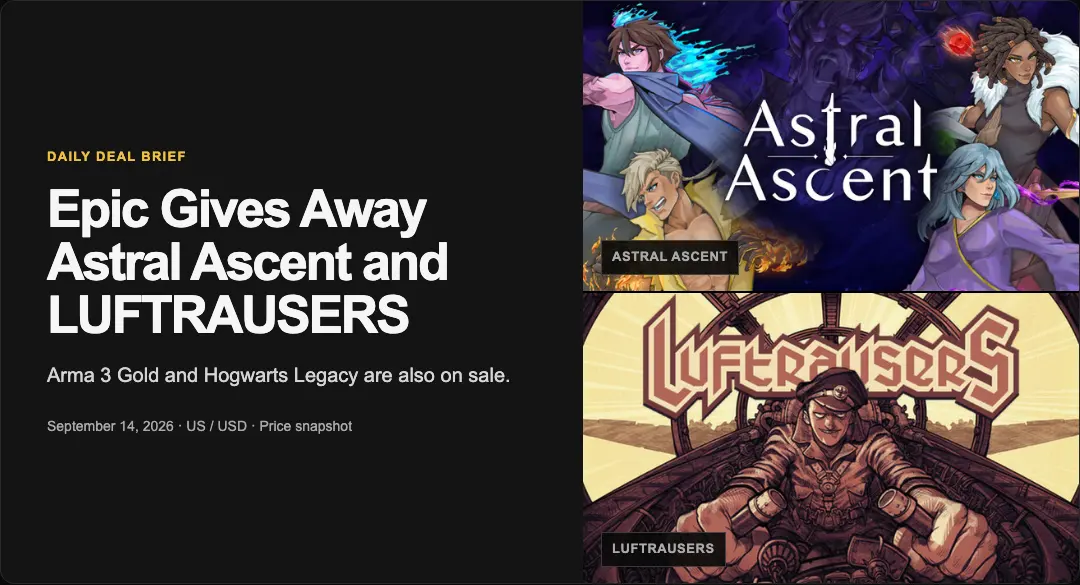
Grab two free PC games before Epic's clock runs out, while Undertale and Divinity: Original Sin 2 are 75% off
Astral Ascent and LUFTRAUSERS are free to keep today, while two of PC gaming's most celebrated RPGs cost less than $14 c




The memory chip subplot is about to drag down the entire consumer electronics story this year.
On February 27, IDC released its latest forecast for the global PC and smartphone markets — and the conclusion is even grimmer than previous pessimistic projections. Caught in a double squeeze of DRAM and NAND flash memory supply shortages and sustained price increases, global smartphone shipments for 2026 will decline 12.9% year-over-year, while the PC market faces an 11.3% year-over-year drop, with any meaningful recovery in both markets pushed back to 2028.

In Q4 2025, manufacturers collectively did one thing: panic stockpile. Bracing for anticipated memory chip price hikes, global PC and smartphone makers adopted aggressive front-loading strategies, sending shipment volumes in both categories sharply higher. This momentum carried into Q1 2026 on the PC side, as OEMs rushed to ship product ahead of broad-based memory and storage price increases — prompting IDC to revise its Q1 PC shipment forecast well above its November 2025 projection.
It sounds like stuffing your inventory bag before fighting the final boss — but that kind of play only buys so much time.

The PC picture is slightly less dire. IDC forecasts a full-year 2026 PC shipment decline of 11.3%, but rising average selling prices should still deliver 1.6% positive revenue growth for the industry. 2027 will be a consolidation year, with the real rebound deferred to 2028. The shipment numbers are ugly, but at least revenue isn't collapsing.
The smartphone side, unfortunately, tells a different story.
In Q1 2026, global smartphone shipments already declined 6.8% year-over-year. As memory prices continue climbing, small and mid-tier vendors are caught in a dual bind: they can't out-compete top players for chip supply, and they have far less room to absorb the cost pressure. IDC expects shipment volumes to fall sharply starting in Q2. The full-year result: shipments down 12.9% and revenue off a modest 0.5%.


Manufacturers are responding by raising average selling prices to pass costs down the chain — but this is directly weakening end demand. Consumers don't have infinite HP; drain the health bar and the game ends. IDC also notes that some smartphone industry revenue figures appear stable only because of inflated ASPs, and therefore hold limited real-world reference value.
Looking ahead, IDC forecasts 1.9% modest growth for the smartphone market in 2027, followed by a stronger 5.2% rebound in 2028.
IDC's report also flags that the surge in high-end memory demand driven by AI compute expansion is squeezing consumer electronics production capacity and supply — this is not a short-term cyclical fluctuation, but a structural reshaping of global semiconductor capacity allocation. The supply chain vulnerabilities of small and mid-tier vendors have been fully exposed in this crisis, and the trend toward further industry consolidation at the top may well accelerate.


Commenti 0
Ci interessa la tua opinione
Partecipa alla discussione e condividi la tua opinione su questo gioco.
Ancora nessun commento. Scrivi il primo.