
Aktualność
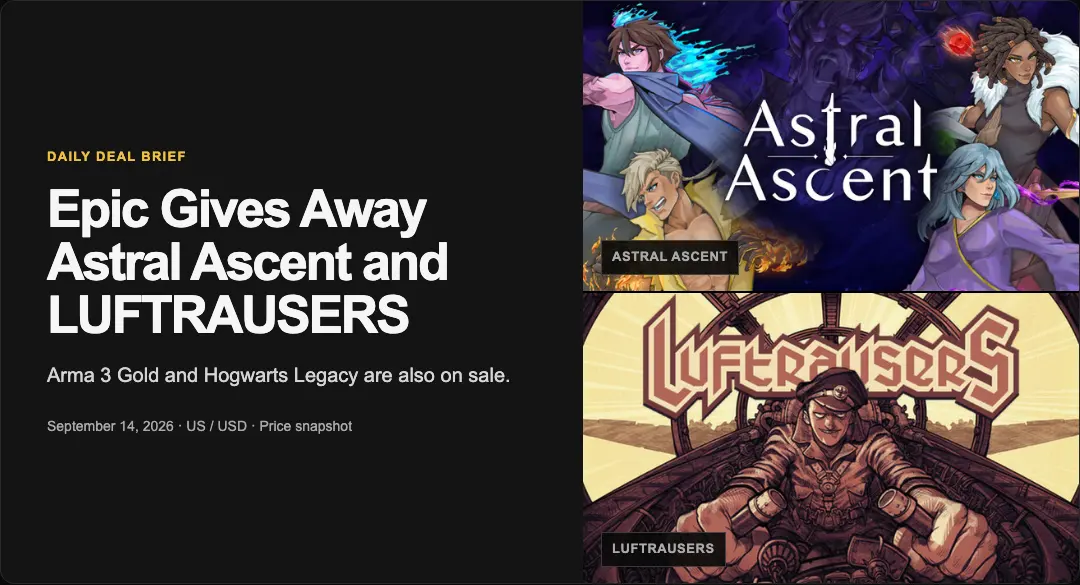
Grab two free PC games before Epic's clock runs out, while Undertale and Divinity: Original Sin 2 are 75% off
Astral Ascent and LUFTRAUSERS are free to keep today, while two of PC gaming's most celebrated RPGs cost less than $14 c




Sometimes when I’m clearing a map all the way to the end, the most annoying thing isn’t that the monsters are too strong, but that little path that looks so close, only to be blocked by an invisible wall. Lately, when looking at the AI chip industry chain, I’ve had that same familiar sense of frustration. Everyone is sprinting ahead focused on GPUs, HBM, and advanced process nodes, but if you follow the packaging path a little further, you realize that the real choke point at the mountain pass is actually a layer of insulating film called ABF.
It sounds like some minor map-edge material, but in reality it is the bridge between silicon chips and PCB circuits. Without it, high-frequency signals are easily disrupted, and chips may even fail outright. In gaming terms, it’s not the main city or the BOSS room, but it’s like the only mountain pass connecting two continents. Usually it doesn’t stand out, but once it’s blocked, there’s no advancing into the entire region beyond it.
What’s even more striking is that this critical material is almost entirely controlled by a single Japanese company, Ajinomoto, which holds more than 95% of the market. The only potential competitor, Sekisui Chemical, entered the field in 2014 and still has only about 5% market share today. This structure is less like an open world and more like a linear level with only one main path. No matter how much players want to explore a detour, there simply isn’t a second mature route outside the map.
And the issue isn’t just monopoly. It’s that the AI era has pushed ABF consumption to a whole new level. Traditional PC chips only require a few layers of ABF, but AI accelerators, because of their large packaging size, directly raise substrate layer counts to 8 to 16 layers. High-performance CPUs can use more than 10 times as much ABF as ordinary PC substrates. You can think of it this way: in the past, people were just building two-lane roads across flatlands, but now everything is suddenly being replaced with elevated cross-sea highways. Naturally, the material consumption is on a completely different scale.
But the map is expanding too quickly, while resource nodes aren’t respawning fast enough. According to current forecasts, annual ABF demand will grow by 40% in 2027, while supply will increase by only 12%, leaving a gap of 26%; by 2028, that gap could widen further to 46%. Ajinomoto is of course also adding capacity, with plans to invest 25 billion yen before 2030 to expand production capacity by 50%. But with AI computing demand maintaining double-digit annual growth, this pace of catch-up is clearly still struggling.
An even more realistic scene is that hyperscale cloud service providers have already begun using prepayments and long-term agreements to lock in capacity. Put bluntly, it’s like when a hot new server opens and the big guilds immediately reserve all the core resource spots, leaving late-arriving small and mid-sized players to queue up on the outskirts. For chip companies, server manufacturers, and even the entire industry that depends on AI infrastructure, ABF is shifting from a behind-the-scenes material into a ticket that determines delivery schedules.
Compared with the chip shortage that people became familiar with in previous years, bottlenecks like ABF are more hidden and harder for ordinary people to notice right away. Everyone understands wafer fab expansion, and GPU shortages are easy to perceive, but deep-layer nodes like packaging materials often go unnoticed until the entire chain starts dropping frames, and only then does the outside world realize that the problem was buried here all along. For those watching the AI industry, the next competition may be not just about computing performance specs, but about who can lock in these seemingly inconspicuous yet actually map-access-defining key materials first.


Komentarze 0
Chętnie poznamy Twoje zdanie
Dołącz do dyskusji i podziel się opinią o grze.
Brak komentarzy. Dodaj swoją opinię.